Stop leaving money in the Tax Trap.
If most of your retirement sits in a 401k, 403b, 457, IRA or TSP, have you ever run the numbers on what the IRS takes on the way out? Marcus Eligan helps DMV families find their Wealth Gap and engineer a tax-free retirement before the bill comes due.
What brings you here today?
Pick the one that sounds like you. Every path ends in the same place: a plan built around your family.
Where does your money live, and who gets paid when it comes out?
Every dollar you own sits in one of three buckets. Each one has a different deal with the IRS. Most families we meet have most of their retirement in the middle one.
Liquid
Taxed every year- Savings, CDs and money market
- Interest is taxed as you earn it
- Keep 3 to 6 months of expenses here. Above that it's Idle Money losing ground to inflation
Tax-Deferred
The Tax Trap- 401k, 403b, 457, IRA and TSP
- Every dollar out is taxed as ordinary income
- Withdrawals can make up to 85% of your Social Security taxable and trigger Medicare IRMAA surcharges
- Required minimum distributions force money out starting at 73 or 75
Tax-Free
The goal- Roth IRA, Roth 401k and properly structured cash value life insurance (IUL)
- Qualified withdrawals and policy loans are not taxable income
- Doesn't count toward Social Security taxation or IRMAA
- No required minimum distributions
The rules changed. Your plan should look at all three.
Your mortgage, your insurance and your retirement are one connected system. A decision in one moves the others. That's why every client gets reviewed on all three, by one strategist licensed in mortgage and insurance who coordinates with your CPA and investment professional.
Cost of Capital
What every dollar you owe really costs you, and whether the equity in your home is working or sitting idle.
Protection
Life insurance with Living Benefits for chronic, critical and terminal illness, so a health event doesn't drain your retirement.
Bucket 3
Moving future income out of the Tax Trap and into tax-free territory before Social Security and Medicare start.
Eight ways we engineer your wealth.
Every strategy connects back to one goal: more of your retirement income in Bucket 3, less of it shared with the IRS.
Wealth Gap Diagnostic
A deep review of your 3 Buckets, your mortgage and your coverage that puts a dollar figure on what your current setup is costing you.
Learn moreEquity Engineering
Your home may be your largest asset sitting idle. We run the math on whether that Idle Equity should stay put or go to work.
Learn moreBucket 3 & IUL Planning
Build tax-free retirement income with indexed universal life: market-linked interest, a 0% floor, and Living Benefits.
Learn morePremium Financing
For high-net-worth families and business owners: a lender pays the premiums on a large policy while your capital stays invested.
Learn more401k, 403b, 457 & TSP
For private, teacher, public and federal employees. We compare your options for an old or current plan, from leaving it alone to a Roth conversion, and document why.
Learn moreMortgage & Cost of Capital
Not just a rate. A Cost of Capital analysis on every dollar you owe, through Mortgage Experts, Marcus's mortgage brokerage.
Visit Mortgage ExpertsEstate & Legacy Planning
Wills and trusts coordinated with a licensed estate planning attorney for MD, DC and VA families. A blueprint needs a legacy plan.
Learn moreThe Freedom Sprint
Your debt-free date, a 90 day plan to get there, and where your home and credit fit. Then the freed-up cash flow goes to work.
Learn moreNot sure where to start?
Run the Wealth Gap Calculator and see what Bucket 2 could cost you in Social Security tax and Medicare premiums.
Run the calculatorThe tax bills most families never see coming.
They don't show up on a 401k statement. They show up in retirement, when it's hardest to fix them.
The Social Security Tax Trap
When 401k, IRA or TSP withdrawals push your income past federal thresholds, up to 85% of your Social Security benefit becomes taxable. The thresholds have never been raised for inflation.
Medicare IRMAA Surcharges
Higher income raises your Medicare Part B and Part D premiums. Medicare looks back two years, so a big withdrawal at 63 can raise your premiums at 65.
From math to decision in three steps.
Discovery Call
A free 30-minute conversation. Where are you now, where do you want to be, and what's in the way? No homework required.
Wealth Gap Diagnostic
We map your 3 Buckets, your mortgage and your coverage, then show you the dollar gap and the leaks causing it.
Your Blueprint
You decide what to fix first. We implement the mortgage and insurance pieces, coordinate the rest with your CPA and investment professional, and review it with you every year.
You worked hard for your money. You deserve a plan that keeps more of it.
You did what you were told: save in the 401k, pay down the house, buy the coverage at work. The rules changed while you were doing it. Marcus Prescott Eligan has spent more than 20 years helping DC, Maryland and Virginia families look at their home, their protection and their retirement together, the Tri-Pod of Finance, so every dollar has a job.
His signature move is Equity Engineering: looking at the Idle Equity in your home and the Cost of Capital on everything you owe, then deciding with you whether those dollars belong in a tax-free retirement engine instead. He works with families, teachers and public employees, federal employees and real estate investors across the DMV.
"Visiting hours are over."
Picture a hospital bed. Balloons in the corner, cards from work. Around 8:30 the nurse says visiting hours are over, and everybody leaves. You are not thinking about your health. You are thinking, who is paying the mortgage this month?
That is why Marcus builds every plan around one question: what happens to your family's money while you are still alive? A Family Bank is Bucket 3 with your family's name on it. Money you can reach without asking a lender, and protection that can pay you while you are living, not only after.
Marcus's personal experience, not a promise of results. Policy loans and withdrawals reduce cash value and the death benefit. Living benefits are advances on the death benefit and depend on the carrier and product.
What clients say about working with Marcus.
These reviews come from Mortgage Experts home loan clients on Google.
"Marcus and his team worked really hard to get me through the final underwriting to close on my home. The overall process had me stressed but Marcus assured me the home was mine and he worked profoundly to make sure it happened."
"Marcus and Tabby were truly outstanding in allowing me and my family to experience home ownership yet again! This is my second home purchase with Mortgage Experts. When I didn't think I could qualify due to credit concerns, they worked their magic."
"I've worked with Marcus Eligan on numerous occasions and his professionalism, experience, and willingness to go the extra mile to obtain the best results is remarkable. I look forward to working with Marcus and his team on future endeavors."
Know someone who is renting, or sitting on a 401k they have never looked at? Send them my way: 301-945-8300.
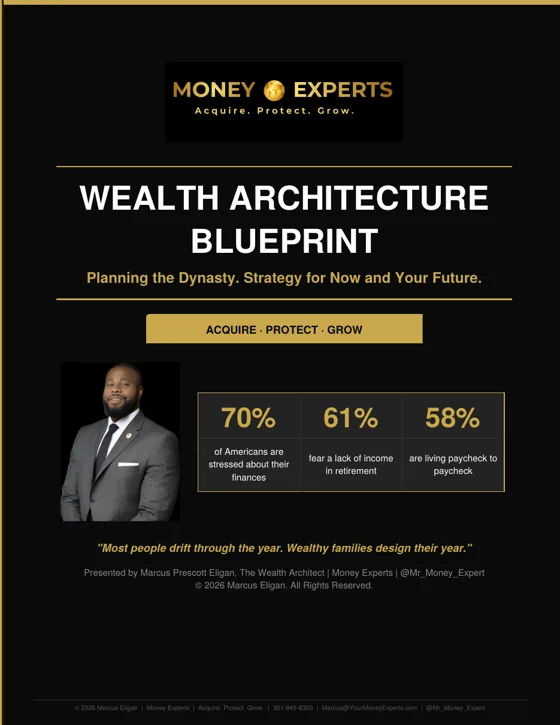
Your Annual Wealth Architecture Blueprint.
The same 10-page planning guide and goals spreadsheet our team uses with clients. Map your 6 Pillars, audit your 3 Buckets and set goals that pass one test: does it grow your net worth or protect your assets?
Questions we hear before the first call.
Is the discovery call really free?
Yes. It is a 30 minute phone call with Marcus at no cost and with no obligation. You leave with a clear next step either way.
How does Marcus get paid?
On a home loan, Mortgage Experts is paid through the loan, and every cost is disclosed on your Loan Estimate before you commit. On life insurance and annuities, the insurance company pays Marcus a commission when a policy is placed. The discovery call, the calculator and the Wealth Gap Diagnostic cost you nothing.
Is Marcus a financial advisor?
Marcus is a licensed mortgage loan originator (NMLS #189199) and a licensed life insurance producer in Maryland, Washington, DC and Virginia. He is not a registered investment adviser, and he does not manage investments or give tax or legal advice. He works alongside your CPA, investment professional and estate attorney.
Do I need to bring anything to the call?
No homework required. A recent mortgage statement or a 401k or TSP statement helps if you have one handy, but a ballpark number is fine.
Do I have to come into the office?
No. The discovery call is by phone, and most of the work happens by phone or video. You are welcome at the office in Upper Marlboro if you prefer to meet in person.
What if I'm not ready to do anything yet?
That is fine. Many people start with the free calculator or the Blueprint. If your numbers show you are on track, we will tell you that too.
What would it mean to finally know your number?
Your Wealth Gap is the dollar amount your current setup is costing you in taxes, interest and missed growth. The discovery call is free, takes 30 minutes, and you'll leave knowing where you stand.
Prefer to talk now? Call or text 301-945-8300